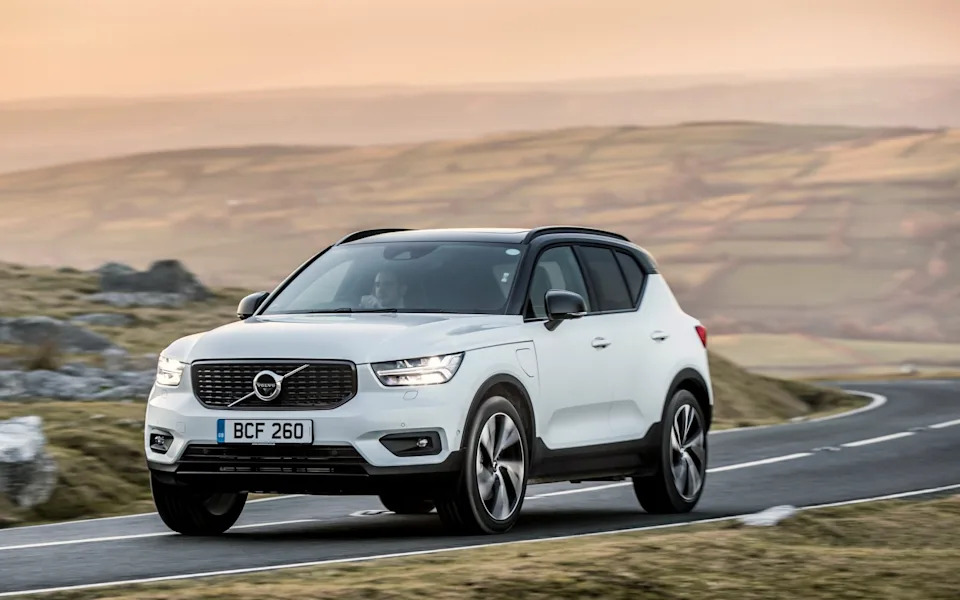
Ask the Expert: Has my insurer penalised me for my disability?The TelegraphAlex RobbinsTue, September 15, 2026 at 6:30 AM UTCAdd us on GoogleA stroke survivor was told their wife could not benefit from their years of no-claims history - John LambDear Alex,My wife and I have one car, insured in my name with her as an additional driver. However, I suffered a stroke in January and have had my licence revoked. I informed my insurer, which acknowledged this in writing. My renewal is now due and my insurer offered a slight reduction, but based on me as the main driver with my wife as an additional driver. When I phoned to correct this, they re-quoted with my wife as the main driver but, instead of the slight reduction in premium, they now quoted a 20 per cent increase, apparently because my no-claims bonus no longer applies. Is this normal? It seems unfair that the no-claims bonus has been forfeited in this circumstance and I feel penalised for my disability.– AKDear AK,I'm afraid it is normal and entirely in keeping with the way insurance works in the UK. Think of it this way: while we talk about car insurance, insurers don't cover the car – they insure the driver. That means the no-claims bonus usually only applies to the person named as the main driver on the policy – not to all the drivers.AdvertisementAdvertisementThus, it's completely normal that your wife, who evidently hasn't been the named driver on a policy for a number of years, doesn't have a no-claims bonus and, as a result, the insurer will not levy the discount it would otherwise have given you.However, it's a shame the insurer was unable or unwilling to offer any discount in recognition of your wife's long driving career. Some insurers are willing to countenance this in recognition of the fact that many people spend long periods as named drivers, not accruing their own no-claims bonus. It seems your insurer is not one of them.You should bear in mind that you don't have to stay with that insurer. If it is unwilling to offer a discount, there's no harm in shopping around for one that might.You might even find you get a better deal as a new customer with a different insurer, irrespective of the no-claims discount. After all, insurers rarely reward loyalty these days and the best deals are usually offered to new customers, which is why it makes sense to shop around for the best deals each time your renewal comes up, rather than simply continuing to renew with the same insurer each year.AdvertisementAdvertisementYou might also consider consulting an insurance broker, who might be able to take account of your circumstances and put the case to an underwriter for your wife to be offered similar terms to a no-claims discount.In short, don't accept your current insurer's way of doing things; shop around and you might find someone else is more willing to recognise your wife's clean driving history and reward her for it.One reader was left facing a £12,000 bill after their six-year-old XC40 suffered catastrophic engine failureDear Alex,My 2020 Volvo XC40 Hybrid has done 80,000 miles and has been serviced regularly at a Volvo dealer. We have now been told we need a new engine at a cost of £12,000, including parts and labour, having already spent £700 on an investigation that failed to reveal anything definitive other than that it is burning oil, possibly due to deterioration of the piston rings.Volvo UK has said that it will only deal with the dealership and that, before deciding whether to contribute, it will require the engine to be taken apart, at a further cost of £900, to discover the fault. So far, we have spent six weeks trying to get an answer about the nature of the fault and now Volvo wants more money to investigate further. What do you think?AdvertisementAdvertisement– PBDear PB,I was disappointed to hear, firstly, that Volvo would not talk to its customer about the case and that it wanted you to pay £1,600 in an attempt to find out conclusively what was wrong with a car that, at only six years old, was unlikely to require a new engine.I offered to speak to Volvo to see whether I could get any further. It then agreed at least to cover the additional cost of the diagnostic work. Unfortunately, the diagnosis only confirmed that the engine had failed catastrophically and that a new one was required.Volvo offered a further contribution of 15 per cent of the total bill. You said that you felt this wasn't appropriate given the car's full history of servicing within the main dealer network, as well as the fact that the dealer's report made clear that there was nothing more you could have done to prevent the fault occurring.AdvertisementAdvertisementDespite this, Volvo was not willing to increase its offer and, after nine weeks without a car, you decided that you had no real choice but to approve the work, pay the outstanding bill (which by now had reached almost £12,000, even taking into account Volvo's contribution) and move on.You added that you believe the main dealer, Waylands, did its best to help with the overall costs. But you also told me that you were very disappointed that Volvo was not prepared to offer more in the way of compensation, especially given your belief that the report you obtained from the main dealer suggested that the issue was a manufacturing defect.I think you made the right choice given the circumstances; frankly, I'm not sure what else you could have done.On the one hand, manufacturers will always argue that they have no obligation to provide any goodwill on a car that's so far outside its warranty period. On the other, buyers such as yourself quite reasonably expect not to have to pay out a five-figure sum to repair a six-year-old car.AdvertisementAdvertisementI asked Volvo whether it was willing to comment on your case, but have yet to receive a response.Do you have a question? Contact carsadvice@telegraph.co.ukTry full access to The Telegraph free today. Unlock their award-winning website and essential news app, plus useful tools and expert guides for your money, health and holidays.

 +30 others