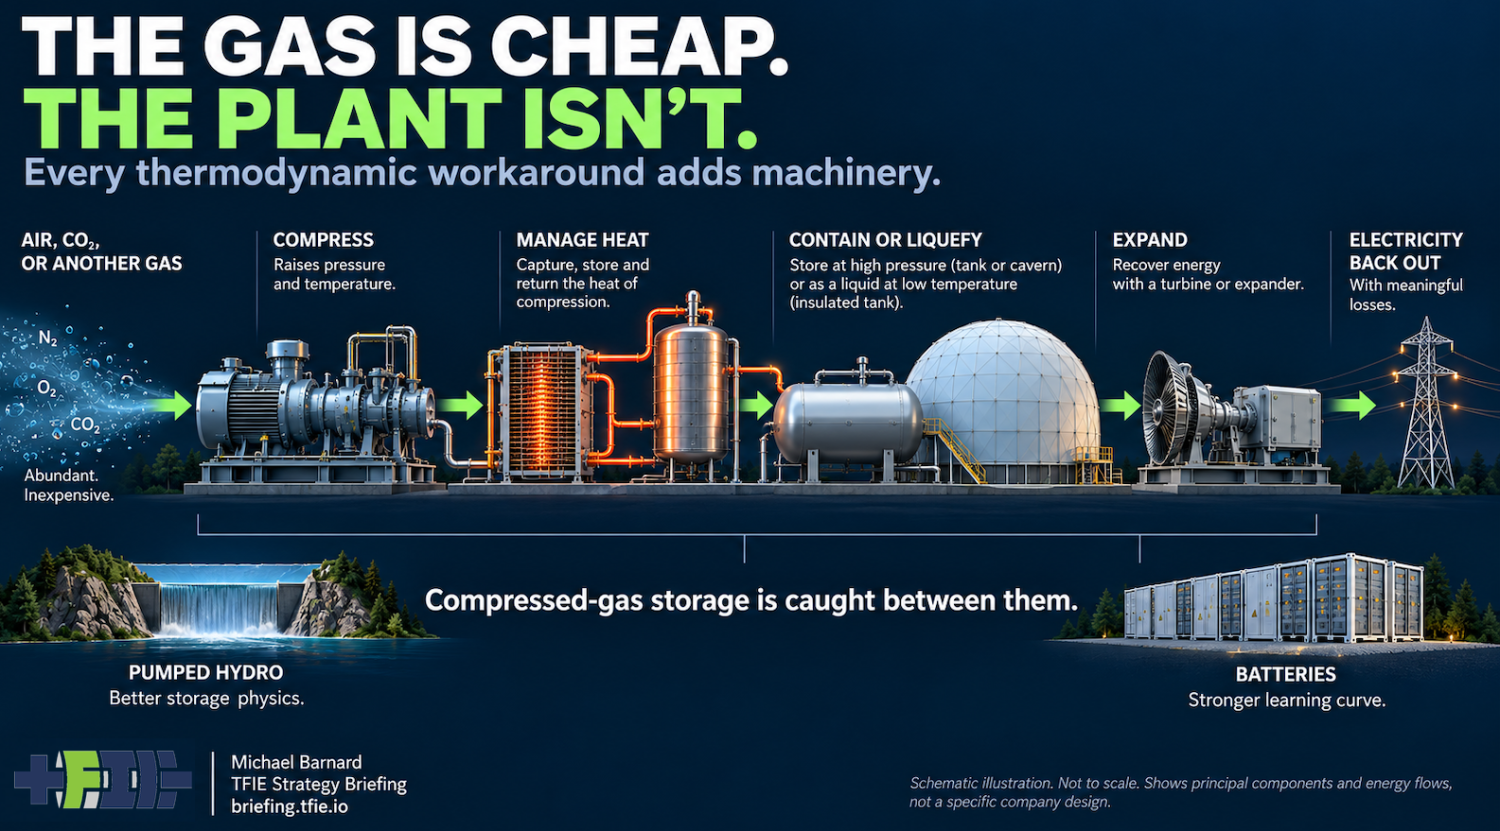
Two years ago I called compressed-gas electricity-storage claims mostly hot air. Since then the sector has produced exactly the sort of evidence that should force a reassessment rather than a repetition of the old argument. China has commissioned the 600 MW / 2.4 GWh Huai’an compressed-air demonstration, Hydrostor has pushed its 500 MW / 4 GWh Willow Rock project through California certification, Highview Power has moved its 50 MW / 300 MWh liquid-air plant into construction, and Energy Dome has advanced a first-of-a-kind 20 MW / 200 MWh CO₂ Battery in Sardinia. These are considerably more serious than laboratory rigs and PowerPoint diagrams, but a handful of demonstrators and first-of-a-kind plants is not an industry scaling. Building one huge machine proves surprisingly little about whether anybody should build the next hundred. China also built Energy Vault’s giant gravity-storage machine at Rudong. Physical existence did not rescue that architecture from its capital cost, footprint, mechanical complexity, and operating burden. Huai’an deserves the same analytical discipline. It demonstrates that China can build an enormous advanced CAES plant and acquire engineering experience from it. It does not demonstrate that CAES is the storage architecture grid operators should prefer when batteries or pumped hydro are available. The physics keep creating machinery. Compressing gas creates heat, so efficient CAES needs thermal stores, heat exchangers, piping, and controls to capture that energy and return it before expansion. Liquid-air storage deals with the huge volume of gaseous air by refrigerating it across a genuinely cryogenic phase transition, then adds insulated tanks, heat recovery, cold recovery, compressors, and expanders to recover as much of the input electricity as practical. Energy Dome made the most intelligent thermodynamic choice in this family by switching to CO₂, because carbon dioxide can be condensed under much more manageable industrial temperatures and pressures. That is a genuine improvement. It still leaves a process plant that has to compress, cool, condense, store, reheat, expand, and contain the working fluid. The full reassessment in TFIE Strategy Briefing goes back through the thermodynamics, China’s new CAES plants, Hydrostor, liquid-air storage, Energy Dome’s CO₂ architecture, lifecycle claims, and the difference between ordinary first-of-a-kind improvement and a genuine manufacturing experience curve. All that machinery would matter less if the resulting storage cycle were unusually good. It isn’t. Pumped hydro also involves substantial civil engineering, but mature systems start around 80% round-trip efficiency while storing energy through the elevation of liquid water. Batteries have meaningful balance-of-plant costs too, but cells, modules, inverters, and controls emerge from manufacturing systems capable of extraordinary repetition. The IEA reports that average global BESS prices in 2025 had fallen to one-third of their 2020 level. Compressed-gas storage sits between these reference classes, carrying much of the process and civil-engineering burden of infrastructure without pumped hydro’s mature efficiency or batteries’ manufacturing mechanism. Hydrostor is a particularly clear example of why clever engineering is not the same thing as compelling economics. Conventional CAES likes favourable underground geology such as salt caverns. Hydrostor broadens the siting possibilities by excavating a purpose-built hard-rock cavern and using water to maintain hydrostatic pressure as the air volume changes. The California Energy Commission describes Willow Rock as a 500 MW net, 4,000 MWh net facility with four compressor and turbine trains, common thermal storage tanks, an excavated cavern, and a 19-mile transmission connection. Its staff assessment puts round-trip efficiency at about 60%. That is an extraordinary amount of infrastructure to return around three-fifths of the electricity used to charge it. There may be specific locations where poor pumped-hydro geography and a strong need for eight-hour capacity make that trade worthwhile. Different siting constraints can have value. But solving salt-cavern dependence by excavating a bespoke hard-rock cavern does not transform compressed-air storage into a manufactured product. The mechanism used to expand the geography moves still more of the capital into excavation, geotechnical work, underground access, water management, and project-specific construction. Liquid-air storage does not escape the same problem. My earlier treatment understated how much modern designs can recover through sophisticated heat and cold storage, and that was worth correcting. But a 2025 critical review of liquid-air energy storage still places standalone systems broadly around 50%–60% round-trip efficiency and identifies limited economic benefits, while hybrid systems improve substantially when they can draw on external heat or cold. Another 2025 systematic review identifies low efficiency, poor economic performance, technical complexity, and limited engineering deployment as continuing barriers. That external heat or cold can make a project perfectly rational. Liquid-air storage next to LNG regasification, for example, may exploit cold that would otherwise have little value. Industrial waste heat may improve expansion efficiency. But at that point the storage economics depend on a specific neighbouring industrial process, its operating schedule, the temperature of the energy stream, and its counterfactual value. That can produce good projects without producing a broadly replicable storage technology. Energy Dome deserves more credit for choosing CO₂ because it removes a substantial part of liquid air’s cryogenic burden. But the company’s strongest claims still run well ahead of operating history. Energy Dome advertises more than 70% net round-trip efficiency, a 30-plus-year lifetime, and no degradation of capacity or performance. The efficiency claim is plausible enough to test. The thirty-year plant-level lifecycle claim is something else entirely because no commercial-scale installation has existed remotely long enough to demonstrate it. The working fluid may not chemically degrade like a battery electrode, but the plant surrounding it contains compressors, turbines, pumps, valves, bearings, seals, heat exchangers, thermal-storage systems, and a huge flexible gas holder. CO₂ molecules surviving indefinitely do not confer immortality on the equipment containing and moving them. A reasonable economic model should include inspections, maintenance, membrane work, major overhauls, and eventual replacement rather than treating “no degradation” as an observed property of a plant that has never operated for anything close to thirty years. The financing evidence deserves the same skepticism. Energy Dome’s Sardinian facility is explicitly being supported as first-of-a-kind utility-scale technology development by the European Investment Bank, alongside strategic and public-policy capital. That is exactly what innovation finance should do: pay to discover whether unfamiliar hardware works at useful scale. It does not establish that mature projects are already commercially competitive on unsubsidized terms. The usual answer to these numbers is the learning curve. Early projects are expensive because they are first-of-a-kind; later projects eliminate engineering mistakes, contingency, procurement friction, and immature supply chains. That is all credible, and repeated projects should become cheaper. But first-of-a-kind to nth-of-a-kind improvement is not automatically a manufacturing experience curve. A BESS cost decline is driven substantially by cells, modules, and power electronics manufactured at enormous volumes for both transportation and stationary storage. Compressed-gas plants still require site preparation, foundations, pressure vessels, thermal stores, piping, heat exchangers, grid interconnection, and field commissioning, while CAES and Hydrostor add significant underground work. Excavation does not become a gigafactory product because another cavern was commissioned somewhere else. That is why projected future costs need mechanisms rather than downward-sloping lines. Which fraction of installed capital can actually migrate into repeatable high-volume manufacture? Which fraction remains ordinary engineering, procurement, construction, and civil work? How much of the first few projects’ cost decline comes from removing first-of-a-kind contingency, and how much can continue after that low-hanging fruit is gone? Those questions become harder, not easier, when battery costs are falling during the same years compressed-gas projects require for development, permitting, financing, excavation, construction, and commissioning. None of this means compressed-air, liquid-air, or CO₂ storage will never find useful applications. Grid requirements differ by geography, duration, electricity prices, network constraints, geology, and available sites. A globally minor technology can still be the sensible answer in a particular location. New demonstrators are useful precisely because they generate evidence that simulations, vendor decks, and small pilots cannot. But scale is a market outcome, not the physical dimensions of a demonstrator. A technology starts demonstrating scale when customers repeatedly choose second, tenth, and hundredth projects because they outperform other ways of buying the same service. The evidence for compressed-gas electricity storage remains nowhere near that standard. The last two years have produced larger machines and reasons to revise parts of my 2024 assessment. They have not produced much evidence of widespread competitive replication against pumped hydro or batteries. The gas remains abundant and inexpensive. The compressors, thermal stores, pressure vessels, refrigeration systems, caverns, foundations, turbines, piping, and commissioning around it remain a plant. And that plant still has to beat the alternatives. Compressed-gas storage remains an also-ran. Read the full reassessment in TFIE Strategy Briefing.