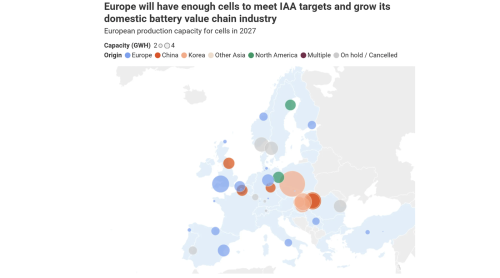
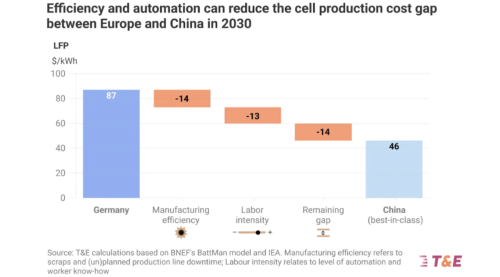
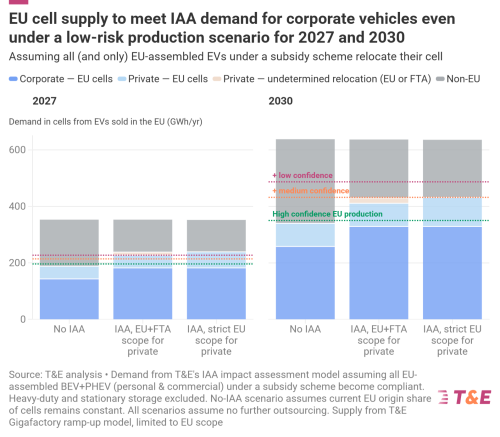
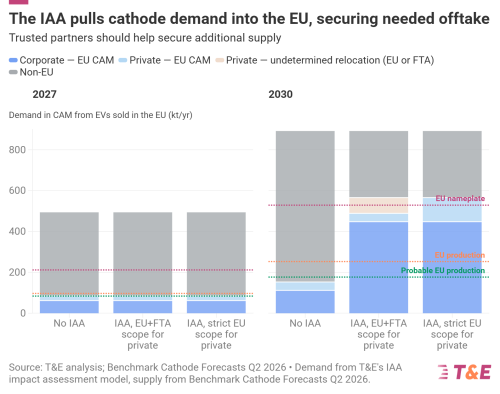
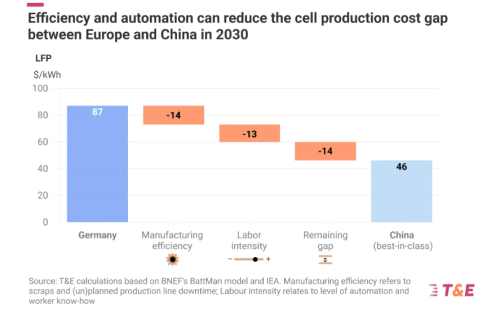
Why battery incentives in the Industrial Accelerator Act (IAA) are essential and achievable. Europe’s battery value chain has experienced several setbacks over the past years. Yet, it doesn’t start from scratch. The Industrial Accelerator Act (IAA) must provide the boost needed to materialise and scale projects. T&E shows how incentives under the IAA are both needed and feasible. T&E has taken a look into the feasibility of the IAA targets as well as a deeper look into Mobility Globa’s study (commisioned by ACEA) that claims a 150GWh “battery gap” by 2028. A quarter since 2022 of announced EU battery cell capacity has been cancelled or shelved. Germany’s pipeline is particularly concerned as its project pipeline for 2035 has halved. EU cell production can meet demand for corporate vehicles by 2027. By 2030, EU cell production alone can power vehicles eligible under support schemes (corporate and private). Cathode demand can be met at least for corporate vehicles with announced capacity by 2030. The IAA will create stable demand and drive project materialisation. T&E has analysed ACEA’s claims and identified fundamental methodological flaws in industry’s arguments — leading to an over-pessimistic conclusion on battery cell capacity in Europe and cost increases linked to onshoring the battery value chain. T&E finds that a quarter of the capacity announced since 2022 has been cancelled or put on hold. Germany is particularly impacted as its 2035 project pipeline has halved. At the moment, non-European entities, predominantly South Korean manufacturers, account for more than 72% of active battery cell manufacturing across the continent. However, Europe is not starting from zero. More than half of the cells in EVs sold on the EU market today are already “Made in EU”. Europe’s battery value chain is specialising in NMC chemistries as well as in LFP. Whilst Europe is further behind on LFP batteries, potential in Europe is substantial: Europe is on track to produce over 100GWh of LFP batteries by 2030 and could reach 140GWh if all potential projects go ahead. By 2027, the EU alone would have sufficient cells to power corporate EVs (modeled on actual expected output, not nameplate capacity). A substantial share of the demand stemming from subsidised private vehicles can also be met with local cell production. In 2030, both demand for corporate and private vehicles can be met with existing cell production. On Cathode Active Material (CAM) production, T&E finds that without further action, China could still retain over 80% of the world’s production in 2035, with only 3% of global cathode production based in Europe. Despite China dominating global supply, several cathode clusters — on LFP and NMC — are emerging in Europe. T&E analysis shows that cathode demand can be met at least for corporate vehicles with announced capacity. However, to accommodate supply for CAM in subsidised private vehicles, trusted partners like Canada and South Korea should be added to the scope. Delaying CAM requirements is highly counterproductive as it would jeopardise local CAM projects from scaling. T&E analysis reveals an even weaker link in Europe’s battery supply chain: precursor CAM (pCAM). Despite its strategic importance and its role in providing offtake for EU refiners and recyclers, minimum thresholds for pCAM are not part of the IAA yet. Of all the pCAM capacity announcements by 2030 (552.6 GWh), only 217.9 GWh are still on track. T&E also looked at industry claims Flexibilities proposed by car-makers — so-called fleet booster proposals — would significantly undermine the IAA’s effectiveness, as reaching watered down IAA requirements with a 70% fleet booster mark is currently possible with minimal strategic shifts. Postponing the cell and CAM mandates would remove the critical pull factors needed for cells and CAM projects. ACEA’s 150 GWh “battery shortage/gap” projected for 2028 is inflated and comes from restrictive accounting assumptions. This gap does not actually represent a physical capacity shortfall, but it is rather a commercial allocation choice by OEMs. By subtracting battery cells exported in EU-assembled cars and excluding cells not currently aligned with local assembly setups, the Mobility Global study underestimates real EU manufacturing capacity. On top of this, demand for vehicles to fall under the IAA is overestimated. Similary, cost increases linked to Made-in-EU batteries, as modelled by carmakers, are overstated. Cost increases will remain limited as cost gaps are not static but will decrease over time, as European battery production scales. T&E estimates the cost differential between EU and Chinese cells will drop by 70% by 2030, adding just €500 to the cost of an average EV. Creating local demand is key as clean tech companies like battery manufacturers and other component producers are going through the so-called valley of death — the phase from going from a pilot plant to mass production — where scrap rates are high as industrial processes are optimised. The IAA can help those companies survive and overcome Chinese overreliance by creating additional demand for domestic players. Key recommendations Keep the cell requirement for 2027-8 in place. Article 13 (strict EU scope for corporate cars) should be kept in its current form as it will ensure the vast majority of the market (60% of EVs) is made in EU. Alternatively, a trusted partner approach with a strict Opt-in criteria can be adopted for private and corporate cars. Keep the CAM requirements for 2030 in place and add trusted partners to the scope. EU CAM projects will not survive without further demand signals. Add a minimum threshold for midstream components: 20% for pCAM and 10% for Anode Active Material (AAM) for 2032, to be met with trusted partners. Building domestic midstream capacity to diversify from China is urgent from a resilience and strategic perspective. This should also include a min. 20% threshold for lithium, nickel, cobalt and graphite. Adopt strict criteria for what counts as a trusted partner in order to alleviate circumvention risks. One condition should be to exclude projects in third countries operated by a country holding more than 40% of global manufacturing capacity. Make batteries in small BEVs mandatory Made-in-EU from 2029/2030 onwards, as Europe’s LFP capacity will be fully sufficient to cover this segment. Reject the OEM’s fleet booster proposal to allow a 70% fleet-wide compliance trigger, as it removes the critical pull factors needed to de-risk cells and CAM projects. To be effective, the IAA needs to unlock Final Investment Decisions. Article from T&E. By Franziska Grüning, Raw Materials OfficerBrussels (EU) Read the briefing. Read the T&E reaction on ACEA’s study.

 +17 others