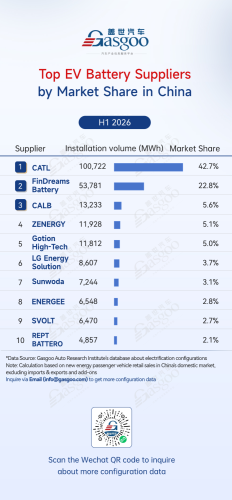
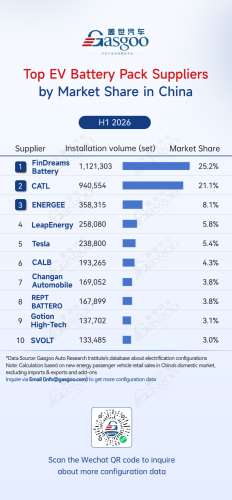
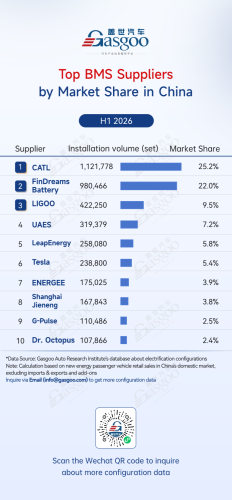
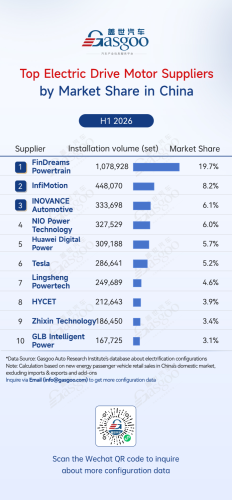
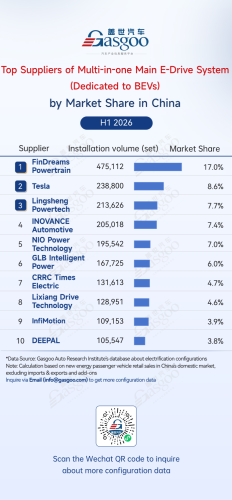
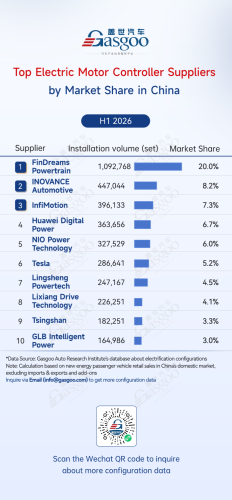
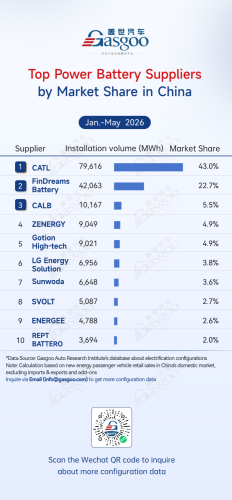
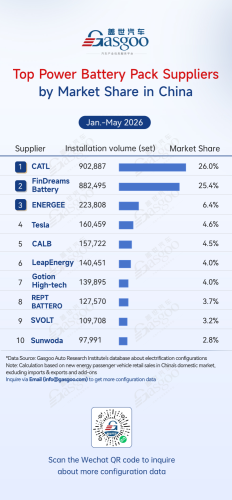
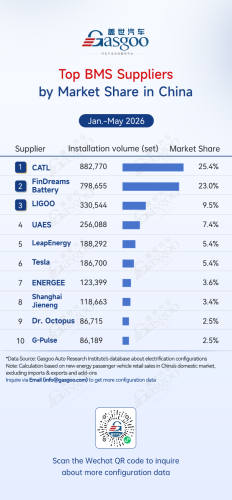
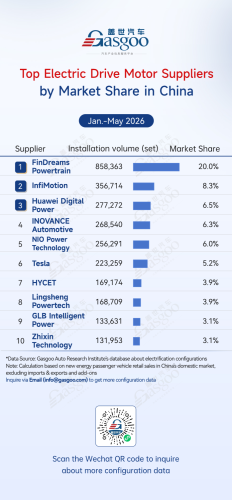
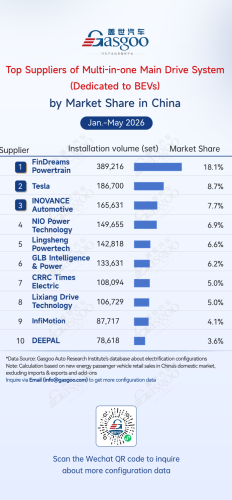
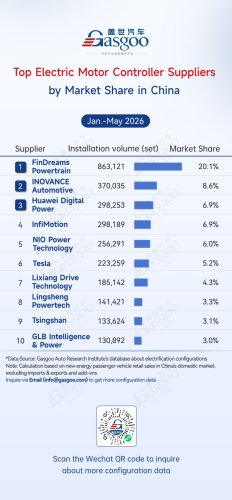
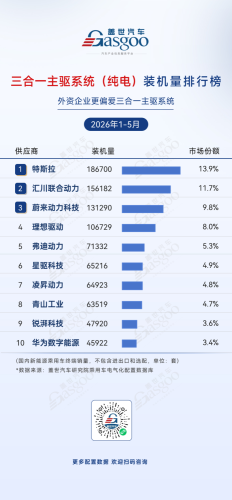
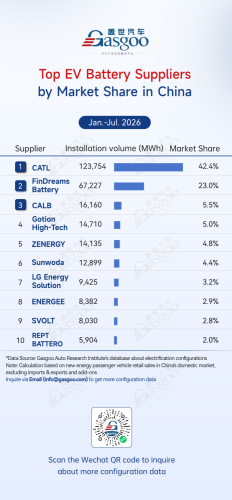
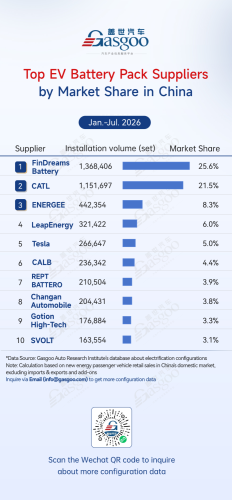
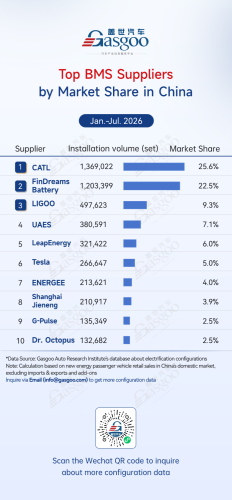
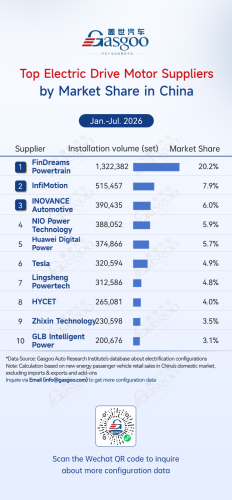
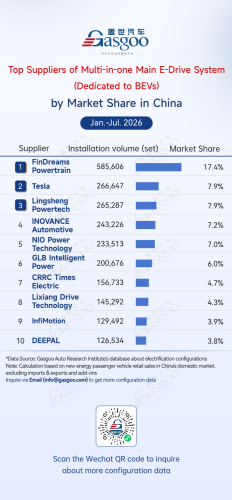
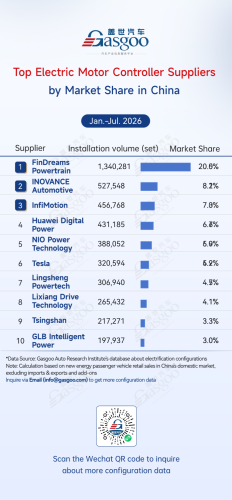
According to Gasgoo Automotive Research Institute, China's new energy passenger vehicle electrification supply market continued to expand from January to July 2026, with vertical integration emerging as a key industry trend. Battery packs, BMS, drive motors, motor controllers, and integrated e-drive systems all saw rapid growth in automaker in-house capabilities. Some leading automakers ranked high in the market, benefiting from their vehicle sales volumes, while third-party Tier 1 suppliers competed alongside automakers' in-house divisions. Competitive tiers varied across segments, the adoption of integrated e-drive solutions continued to rise, and a dual-track development model combining in-house development with external supply became increasingly established.Top EV battery suppliersCATL: 123,754 MWh installed, 42.4% market shareFinDreams Battery: 67,227 MWh installed, 23.0% market shareCALB: 16,160 MWh installed, 5.5% market shareGotion High-tech: 14,710 MWh installed, 5.0% market shareZENERGY: 14,135 MWh installed, 4.8% market shareSunwoda: 12,899 MWh installed, 4.4% market shareLG Energy Solution: 9,425 MWh installed, 3.2% market shareENERGEE: 8,382 MWh installed, 2.9% market shareSVOLT: 8,030 MWh installed, 2.8% market shareREPT BATTERO: 5,904 MWh installed, 2.0% market shareFrom January to July 2026, China's new energy passenger vehicle power battery market remained highly concentrated, with a clear structure of "two leading players followed by intense competition among the second tier." CATL ranked first with 123,754 MWh installed and a 42.4% market share, followed by FinDreams Battery with 67,227 MWh and a 23.0% share. Together, the two accounted for 65.4% of the market, reinforcing their leading positions. CALB, Gotion High-tech, and ZENERGY ranked third to fifth, with market shares of 5.5%, 5.0%, and 4.8%, respectively. The gap among the three was within 0.7 percentage points, indicating close competition within the second tier.By supplier type, Chinese companies continued to dominate the market. LG Energy Solution was the only overseas supplier in the top 10, with a 3.2% market share. Sunwoda, ENERGEE, SVOLT, and REPT BATTERO formed the third tier, with shares of 4.4%, 2.9%, 2.8%, and 2.0%, respectively. The top 10 suppliers together accounted for 96.0% of the market, highlighting the market's high concentration.Top EV battery pack suppliersFinDreams Battery: 1,368,406 sets installed, 25.6% market shareCATL: 1,151,697 sets installed, 21.5% market shareENERGEE: 442,354 sets installed, 8.3% market shareLeapEnergy: 321,422 sets installed, 6.0% market shareTesla: 266,647 sets installed, 5.0% market shareCALB: 236,342 sets installed, 4.4% market shareREPT BATTERO: 210,504 sets installed, 3.9% market shareChangan Automobile: 204,431 sets installed, 3.8% market shareGotion High-Tech: 176,884 sets installed, 3.3% market shareSVOLT: 163,554 sets installed, 3.1% market shareFrom January to July 2026, China's new energy passenger vehicle battery PACK market featured a "two strong leaders followed by broad competition" structure. FinDreams Battery ranked first with 1,368,406 sets installed and a 25.6% market share, followed by CATL with 1,151,697 sets and a 21.5% share. Together, the two accounted for 47.1% of the market, giving them a clear advantage at the top. LIGOO and LeapEnergy ranked third and fourth with shares of 8.3% and 6.0%, respectively, trailing the top two by a noticeable margin.Automakers and affiliated suppliers had a significant presence in the PACK segment. Tesla and Changan Automobile ranked among the top 10, with market shares of 5.0% and 3.8%, respectively. Suppliers such as LIGOO and LeapEnergy also held relatively substantial market shares.Top BMS suppliersCATL: 1,369,022 sets installed, 25.6% market shareFinDreams Battery: 1,203,399 sets installed, 22.5% market shareLIGOO: 497,623 sets installed, 9.3% market shareUAES: 380,591 sets installed, 7.1% market shareLeapEnergy: 321,422 sets installed, 6.0% market shareTesla: 266,647 sets installed, 5.0% market shareENERGEE: 213,621 sets installed, 4.0% market shareShanghai Jieneng: 210,917 sets installed, 3.9% market shareG-Pulse: 135,349 sets installed, 2.5% market shareDr. Octopus: 132,682 sets installed, 2.5% market shareFrom January to July 2026, China's new energy passenger vehicle BMS market featured a "two strong leaders followed by broad competition" structure. FinDreams Battery ranked first with 1,369,022 sets installed and a 25.6% market share, followed by CATL with 1,203,399 sets and a 22.5% share. Together, the two accounted for 48.1% of the market, giving them a clear advantage at the top. LIGOO and UAES ranked third and fourth with shares of 9.3% and 7.1%, respectively, forming the second tier.Automakers and affiliated suppliers had a strong presence in the BMS segment. Lingsheng Energy, Tesla, LIGOO, and Shanghai Jieneng all ranked among the top 10, together accounting for 18.9% of the market. Suppliers such as G-Pulse and Dr. Octopus also maintained a meaningful market presence. The top 10 companies accounted for 88.4% of the market, indicating a relatively high level of market concentration.Top electric drive motor suppliersFinDreams Powertrain: 1,322,382 sets installed, 20.2% market shareInfiMotion: 515,457 sets installed, 7.9% market shareINOVANCE Automotive: 390,435 sets installed, 6.0% market shareNIO Power Technology: 388,052 sets installed, 5.9% market shareHuawei Digital Power: 374,866 sets installed, 5.7% market shareTesla: 320,594 sets installed, 4.9% market shareLingsheng Powertech: 312,586 sets installed, 4.8% market shareHYCET: 265,081 sets installed, 4.0% market shareZhixin Technology: 230,598 sets installed, 3.5% market shareGLB Intelligent Power: 200,676 sets installed, 3.1% market shareFrom January to July 2026, China's new energy passenger vehicle drive motor market showed a "one clear leader followed by multiple strong players" structure. FinDreams Powertrain ranked first with 1,322,382 sets installed and a 20.2% market share, maintaining a clear lead over other suppliers. InfiMotion ranked second with 515,457 sets and a 7.9% share. INOVANCE Automotive, NIO Power Technology, and Huawei Digital Power ranked third to fifth, with market shares of 6.0%, 5.9%, and 5.7%, respectively. The second-tier suppliers held relatively similar shares, resulting in close competition.Automakers' in-house production and affiliated supply systems had a strong presence in the drive motor market. NIO Power Technology, Tesla, Lingsheng Powertech, HYCET, and Zhixin Technology all ranked among the top 10, joining FinDreams Powertrain and InfiMotion as key market participants. The top 10 companies accounted for 66.0% of the market, indicating a relatively balanced level of market concentration rather than a highly concentrated competitive landscape.Top suppliers of multi-in-one main drive system (dedicated to BEVs)FinDreams Powertrain: 585,606 sets installed, 17.4% market shareTesla: 266,647 sets installed, 7.9% market shareLingsheng Powertech: 265,287 sets installed, 7.9% market shareINOVANCE Automotive: 243,226 sets installed, 7.2% market shareNIO Power Technology: 233,513 sets installed, 7.0% market shareGLB Intelligent Power: 200,676 sets installed, 6.0% market shareCRRC Times Electric: 156,733 sets installed, 4.7% market shareLixiang Drive Technology: 145,292 sets installed, 4.3% market shareInfiMotion: 129,492 sets installed, 3.9% market shareDEEPAL: 126,534 sets installed, 3.8% market shareFrom January to July 2026, China's new energy passenger vehicle pure-electric integrated main drive system market showed a "one clear leader and multiple competing players" structure. FinDreams Powertrain ranked first with 585,606 sets installed and a 17.4% market share, maintaining a clear lead. Tesla and Lingsheng Powertech tied for second with 7.9% each, followed by INOVANCE Automotive and NIO Power Technology at 7.2% and 7.0%, respectively. The market shares among the leading players were relatively close.Automakers' in-house production and affiliated supply systems accounted for a significant share of the pure-electric integrated main drive system market. Tesla, NIO Power Technology, Lixiang Drive Technology, and DEEPAL all ranked among the top 10, alongside automaker-affiliated suppliers such as FinDreams Powertrain and Lingsheng Powertech. Meanwhile, specialized suppliers including INOVANCE Automotive, GLB Intelligent Power, CRRC Times Electric, and InfiMotion also remained highly competitive.Top electric motor controller suppliersFinDreams Powertrain: 1,340,281 sets installed, 20.5% market shareINOVANCE Automotive: 527,548 sets installed, 8.1% market shareInfiMotion: 456,768 sets installed, 7.0% market shareHuawei Digital Power: 431,185 sets installed, 6.6% market shareNIO Power Technology: 388,052 sets installed, 5.9% market shareTesla: 320,594 sets installed, 4.9% market shareLingsheng Powertech: 306,940 sets installed, 4.7% market shareLixiang Drive Technology: 265,432 sets installed, 4.1% market shareTsingshan: 217,271 sets installed, 3.3% market shareGLB Intelligent Power: 197,937 sets installed, 3.0% market shareFrom January to July 2026, China's drive motor market showed a clear concentration at the top, with FinDreams Powertrain far ahead of other suppliers. It recorded 1,340,281 sets installed and a 20.2% market share, supported by the large vehicle volumes of the BYD ecosystem. Competition in the second tier was highly intense, with InfiMotion, INOVANCE Automotive, NIO Power Technology, and Huawei Digital Power holding shares ranging from 5.7% to 7.9%. Automakers' in-house development and third-party suppliers competed side by side, creating a diversified supply landscape that included both automaker-developed systems and independent Tier 1 suppliers supplying external customers.The motor controller market was characterized by a strong presence of automaker in-house production, which accounted for more than 50% of the market. FinDreams Powertrain also ranked first, with a 20.5% market share. The close integration of motors and controllers has enabled the in-house development of integrated e-drive systems to drive parallel growth in motor control systems. Third-party suppliers such as INOVANCE Automotive and InfiMotion followed, while automaker-affiliated players including Huawei Digital Power and NIO Power Technology also ranked among the top suppliers.

 +62 others