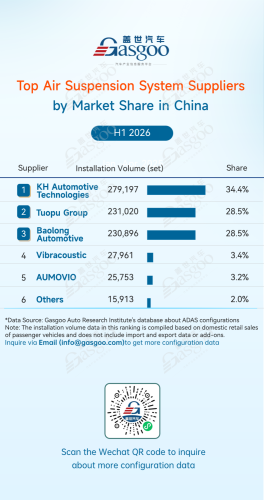
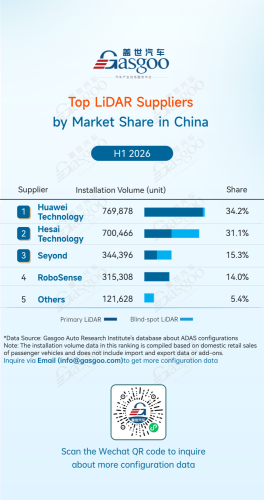
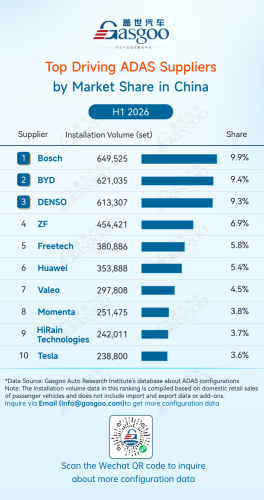
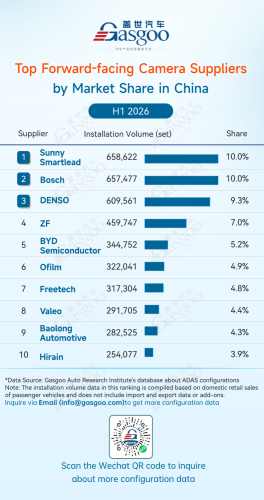
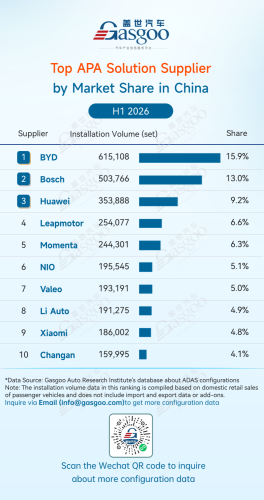
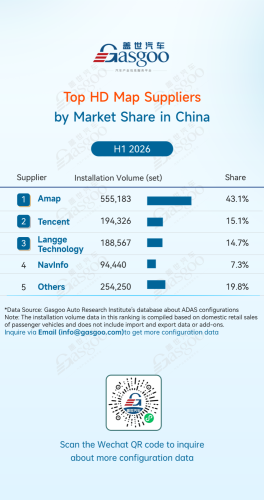
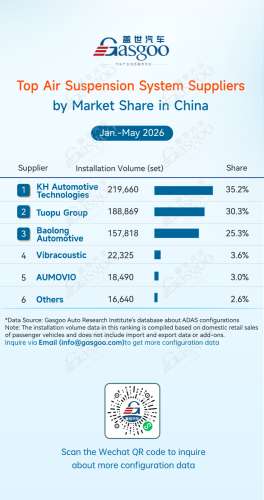
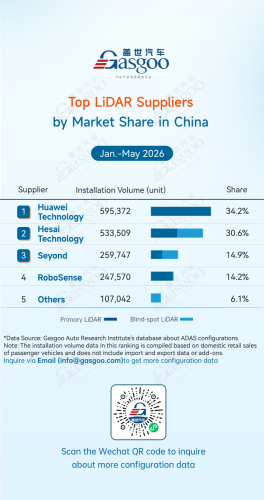
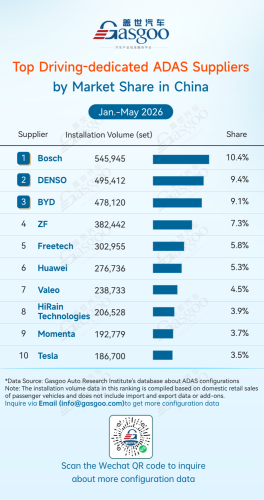
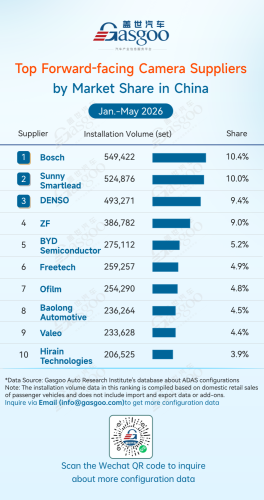
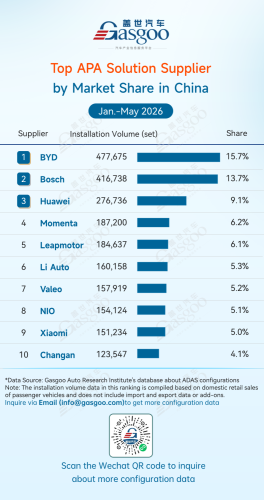
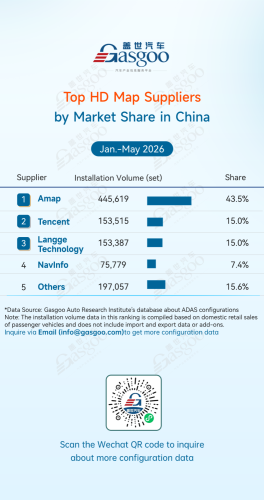
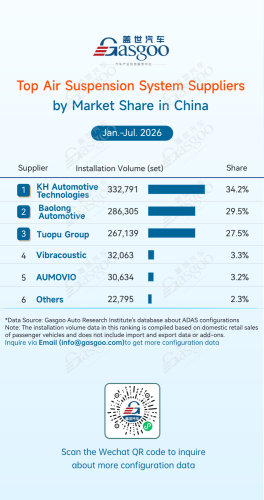
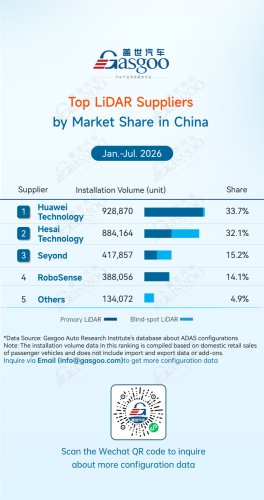
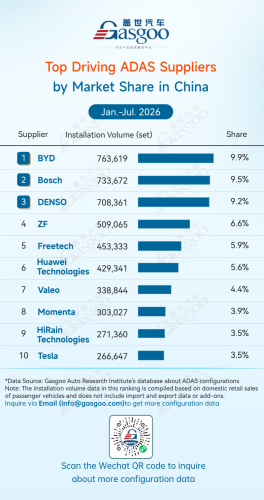
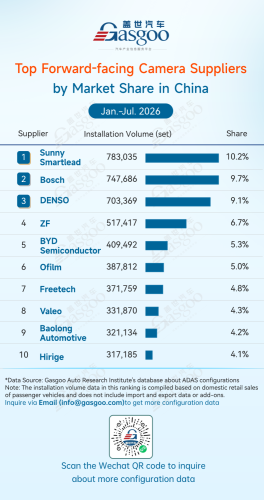
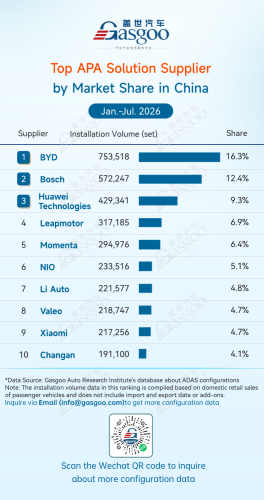
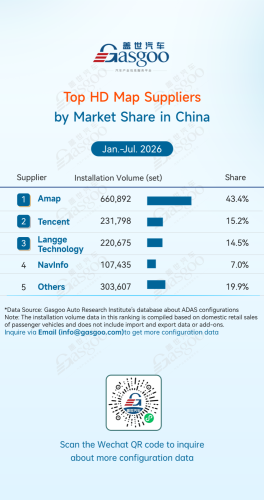
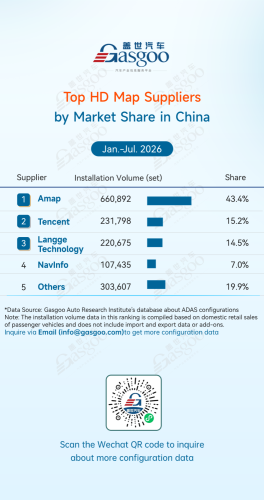
According to Gasgoo Automotive Research Institute, China's passenger vehicle ADAS core component market maintained solid growth from January to July 2026, while the competitive landscape continued to diverge. Segments such as air suspension system, LiDAR, HD map and high precision positioning have developed clear market leaders, with local suppliers taking dominant positions in some areas. Meanwhile, driving-dedicated ADAS, forward-facing cameras and APA solution remained highly competitive, with global Tier 1 suppliers, local companies, technology firms and automakers' in-house solutions all playing an active role.Top air suspension system suppliersKH Automotive Technologies: 332,791 sets installed, 34.2% market shareBaolong Automotive: 286,305 sets installed, 29.5% market shareTuopu Group: 267,139 sets installed, 27.5% market shareVibracoustic: 32,063 sets installed, 3.3% market shareAUMOVIO: 30,634 sets installed, 3.2% market shareOthers: 22,795 sets installed, 2.3% market shareFrom January to July 2026, China's passenger vehicle air suspension market remained highly concentrated, with three leading local suppliers dominating the market. KH Automotive Technologies ranked first with 332,791 sets installed and a 34.2% market share, followed by Baolong Automotive and Tuopu Group with 286,305 sets (29.5%) and 267,139 sets (27.5%), respectively. Together, the three suppliers accounted for 91.2% of the market.Competition between Baolong Automotive and Tuopu Group remained close, with only a 2.0-percentage-point gap. Vibracoustic and AUMOVIO ranked fourth and fifth with shares of 3.3% and 3.2%, respectively, well behind the top three. Overall, the market is increasingly dominated by local suppliers, with scale production, core technologies and customer coverage becoming key competitive advantages.Top LiDAR suppliersHesai Technology: 928,870 units installed, 33.7% market shareHuawei Technologies: 884,164 units installed, 32.1% market shareSeyond: 417,857 units installed, 15.2% market shareRoboSense: 388,056 units installed, 14.1% market shareOthers: 134,072 units installed, 4.9% market shareFrom January to July 2026, China's passenger vehicle LiDAR market remained strong, with a highly concentrated competitive landscape. Hesai Technology ranked first with 928,870 units installed and a 33.7% market share, driven mainly by growth in main LiDAR deployments on models from Li Auto and Xiaomi. Huawei Technologies followed closely with 884,164 units and a 32.1% share, supported by both main and blind-spot LiDAR deployments, particularly across the HIMA lineup. Together, the two suppliers accounted for 65.8% of the market.Seyond and RoboSense formed the second tier, with 417,857 units (15.2%) and 388,056 units (14.1%), respectively. The two suppliers remained closely matched. Seyond benefited from growing deployments of both main and blind-spot LiDAR, particularly on NIO models, while RoboSense's volume was driven mainly by main LiDAR deployments across brands including Zeekr, Denza and Lynk & Co.Top driving-dedicated ADAS suppliersBYD: 763,619 sets installed, 9.9% market shareBosch: 733,672 sets installed, 9.5% market shareDENSO: 708,361 sets installed, 9.2% market shareZF: 509,065 sets installed, 6.6% market shareFreetech: 453,333 sets installed, 5.9% market shareHuawei Technologies: 429,341 sets installed, 5.6% market shareValeo: 338,844 sets installed, 4.4% market shareMomenta: 303,027 sets installed, 3.9% market shareHiRain Technologies: 271,360 sets installed, 3.5% market shareTesla: 266,647 sets installed, 3.5% market shareFrom January to July 2026, China's passenger vehicle driving ADAS market remained highly competitive and fragmented. BYD ranked first with 763,619 sets installed and a 9.9% market share, followed closely by Bosch and DENSO with 733,672 sets (9.5%) and 708,361 sets (9.2%), respectively. The top three each held close to 10%, with no clear market leader.ZF, Freetech and Huawei Technologies ranked fourth to sixth with shares of 6.6%, 5.9% and 5.6%, respectively. Local suppliers and automakers' in-house solutions continued to gain ground, with Freetech, Huawei Technologies, Momenta and HiRain Technologies all ranking among the top 10. BYD's in-house solution ranked first, highlighting the growing role of local and self-developed ADAS solutions.Top forward-facing camera suppliersSunny Smartlead: 783,035 sets installed, 10.2% market shareBosch: 747,686 sets installed, 9.7% market shareDENSO: 703,369 sets installed, 9.1% market shareZF: 517,417 sets installed, 6.7% market shareBYD Semiconductor: 409,492 sets installed, 5.3% market shareOFILM Vehicle Connectivity: 387,812 sets installed, 5.0% market shareFreetech: 371,759 sets installed, 4.8% market shareValeo: 331,870 sets installed, 4.3% market shareBaolong Technology: 321,134 sets installed, 4.2% market shareHirain Technologies: 317,185 sets installed, 4.1% market shareFrom January to July 2026, China's passenger vehicle forward-facing camera market remained highly competitive. Sunny Smartland ranked first with 783,035 sets installed and a 10.2% market share, followed by Bosch and DENSO with 747,686 sets (9.7%) and 703,369 sets (9.1%), respectively. The top three all held shares above 9%, with only a 1.1-percentage-point gap between first and third place.ZF ranked fourth with a 6.7% share, while BYD Semiconductor, Ofilm and Freetech followed with 5.3%, 5.0% and 4.8%, respectively. Local suppliers performed strongly, with BYD Semiconductor, Ofilm, Freetech, Baolong Automotive and Hirige all making the top 10 and collectively accounting for 23.4% of the market.Top APA solution suppliersBYD: 753,518 sets installed, 16.3% market shareBosch: 572,247 sets installed, 12.4% market shareHuawei Technologies: 429,341 sets installed, 9.3% market shareLeapmotor: 317,185 sets installed, 6.9% market shareMomenta: 294,976 sets installed, 6.4% market shareNIO: 233,516 sets installed, 5.1% market shareLi Auto: 221,577 sets installed, 4.8% market shareValeo: 218,747 sets installed, 4.7% market shareXiaomi: 217,256 sets installed, 4.7% market shareChangan: 191,100 sets installed, 4.1% market shareFrom January to July 2026, BYD led China's passenger vehicle APA market with 753,518 sets installed and a 16.3% market share, 3.9 percentage points ahead of Bosch. Bosch and Huawei Technologies ranked second and third with 12.4% and 9.3%, respectively. The top three suppliers together accounted for 38.0% of the market.Automakers and their affiliated solutions were prominent, with Leapmotor, NIO, Li Auto, Xiaomi, and Changan all making the top 10. Momenta ranked fifth with a 6.4% share, while Valeo ranked eighth at 4.7%. Overall, the APA market is seeing growing competition among automakers, technology companies, and traditional Tier 1 suppliers, with automakers increasingly developing parking functions in-house through closer integration of vehicle hardware, software, and intelligent driving systems.Top HD map suppliersAMap: 660,892 sets installed, 43.4% market shareTencent: 231,798 sets installed, 15.2% market shareLangge Technology: 220,675 sets installed, 14.5% market shareNavInfo: 107,435 sets installed, 7.0% market shareOthers: 303,607 sets installed, 19.9% market shareFrom January to July 2026, China's passenger vehicle HD map market remained highly concentrated, with AMap leading by a wide margin. AMap ranked first with 660,892 sets installed and a 43.4% market share, 28.2 percentage points ahead of Tencent. Tencent and Langge Technology ranked second and third with 15.2% and 14.5%, respectively, forming a relatively close second tier.NavInfo ranked fourth with a 7.0% share, while other suppliers collectively accounted for 19.9%. Overall, AMap maintained a clear lead, with Tencent and Langge Technology competing closely behind and other suppliers maintaining a meaningful market presence.Top suppliers of high precision positioning systemASENSING: 1,199,979 sets installed, 35.4% market shareHuawei Technologies: 439,851 sets installed, 13.0% market shareGEESPACE: 219,119 sets installed, 6.5% market shareXiaomi: 214,965 sets installed, 6.3% market shareMCT: 200,055 sets installed, 5.9% market shareOthers: 1,117,982 sets installed, 33.0% market shareFrom January to July 2026, China's passenger vehicle high-precision positioning market showed a "one dominant player, multiple strong contenders, and a fragmented long tail" structure. ASENSING led with 1,199,979 sets installed and a 35.4% market share, 22.4 percentage points ahead of Huawei Technologies. Huawei ranked second at 13.0%, followed by GEESPACE, Xiaomi, and MCT at 6.5%, 6.3%, and 5.9%, respectively.Other suppliers collectively accounted for 33.0% of the market, indicating a fragmented competitive landscape despite the leading position of ASENSING. Overall, ASENSING held a clear lead, while Huawei Technologies and a range of suppliers and automaker-backed solutions competed across the rest of the market.

 +16 others