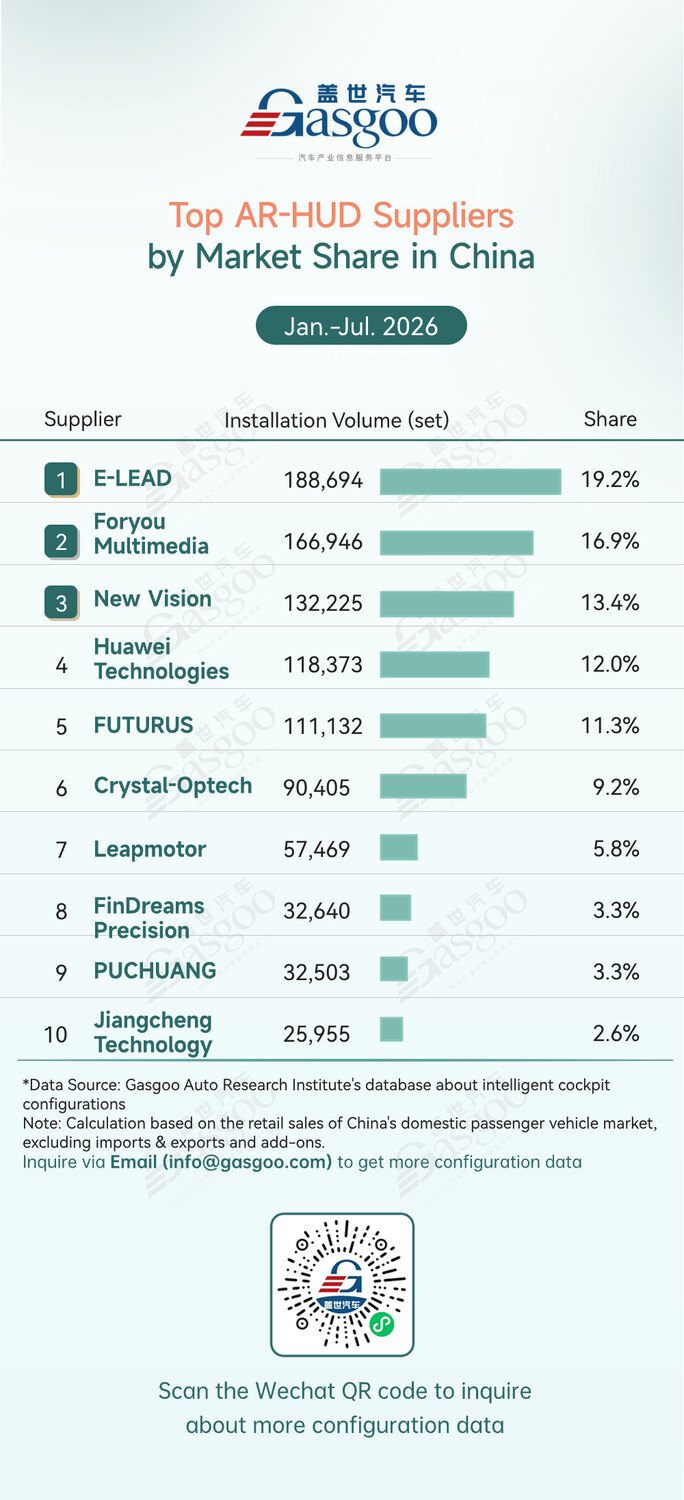
In January–June 2026, China's passenger vehicle smart cockpit market continued to grow rapidly, with competition further intensifying across key segments including cockpit domain controllers, domain control chips, HUDs, center displays, LCD instrument clusters, and voice interaction. Local suppliers continued to strengthen their advantages in hardware integration, system development, and ecosystem collaboration, taking leading positions in several segments. Meanwhile, the chip market remained highly concentrated, while the voice interaction market continued to be dominated by leading players. Overall, smart cockpit competition is shifting from standalone hardware performance toward comprehensive capabilities encompassing hardware-software integration, system development, AI, and ecosystem collaboration. Top cockpit domain controller suppliers Desay SV: 693,679 sets installed, 14.9% market share Bosch: 356,162 sets installed, 7.6% market share Huawei Technologies: 334,956 sets installed, 7.2% market share ECARX: 298,937 sets installed, 6.4% market share Honeycomb Electronics: 251,636 sets installed, 5.4% market share Autolink: 250,976 sets installed, 5.4% market share HARMAN: 245,092 sets installed, 5.3% market share PEGATRON/Quanta (Tesla): 238,800 sets installed, 5.1% market share Foryou General Electronics: 213,780 sets installed, 4.6% market share Flextronics: 181,763 sets installed, 3.9% market share Based on data from January–June 2026, China's passenger vehicle cockpit domain controller market remained highly competitive, with leading suppliers pulling ahead while multiple tiers continued to compete closely. Desay SV ranked first with 693,679 sets installed and a 14.9% market share, leading Bosch by 7.3 percentage points. Bosch and Huawei Technologies ranked second and third with market shares of 7.6% and 7.2%, respectively. Competition was particularly tight among mid-tier suppliers. ECARX ranked fourth with a 6.4% share, followed by Honeycomb Electronics, Autolink, and HARMAN at 5.4%, 5.4%, and 5.3%. The presence of PEGATRON/Quanta (Tesla), Foryou General Electronics, and Flextronics in the top 10 further highlights the diversified supply landscape. Overall, competition is shifting from hardware supply toward system integration, software capabilities, and large-scale production. Top brands of smart cockpit domain controller chip Qualcomm: 3,401,271 units installed, 71.4% market share Huawei Technologies: 355,119 units installed, 7.5% market share SiEngine: 246,977 units installed, 5.2% market share AMD: 242,889 units installed, 5.1% market share MediaTek: 227,662 units installed, 4.8% market share SemiDrive: 94,656 units installed, 2.0% market share Samsung Semiconductor: 71,091 units installed, 1.5% market share Renesas Electronics: 44,649 units installed, 0.9% market share Texas Instruments: 37,078 units installed, 0.8% market share AutoChips: 32,070 units installed, 0.7% market share Based on data from January–June 2026, China's passenger vehicle cockpit domain controller chip market remained highly concentrated. Qualcomm dominated with 3.40 million units installed and a 71.4% market share, maintaining a clear lead over other suppliers. Huawei Technologies ranked second with a 7.5% share, followed by SiEngine, AMD, and MediaTek at 5.2%, 5.1%, and 4.8%, respectively, forming the main chasing group. Local chipmakers are also strengthening their presence. Huawei Technologies, SiEngine, SemiDrive, and AutoChips all ranked among the top 10, with Huawei exceeding 350,000 units and maintaining second place. Overall, Qualcomm's dominance remains strong, while local suppliers continue to expand their presence in the cockpit domain controller chip market. Top HUD suppliers Foryou Multimedia: 633,533 sets installed, 29.8% market share E-LEAD: 216,523 sets installed, 10.2% market share New Vision: 213,583 sets installed, 10.1% market share Crystal-Optech: 198,345 sets installed, 9.3% market share DENSO: 173,199 sets installed, 8.2% market share FUTURUS: 141,558 sets installed, 6.7% market share AUMOVIO: 128,969 sets installed, 6.1% market share FinDreams Precision: 117,985 sets installed, 5.6% market share Huawei Technologies: 96,014 sets installed, 4.5% market share Jiangcheng Technology: 50,854 sets installed, 2.4% market share From January to June 2026, China's passenger vehicle HUD market remained dominated by local suppliers, with leading players competing closely. Foryou Multimedia ranked first with 633,533 sets installed and a 29.8% market share, maintaining a clear lead. E-LEAD and New Vision ranked second and third with shares of 10.2% and 10.1%, respectively, while New Vision also saw strong growth across both standard-fit and optional-fit markets, as well as overseas business. Crystal-Optech ranked fourth with a 9.3% share, keeping it within the core competitive tier. The top four suppliers together accounted for 59.4% of the market, indicating continued concentration among leading players. DENSO, FUTURUS, AUMOVIO, FinDreams Precision, Huawei Technologies, and Jiangcheng Technology ranked fifth through tenth, with shares ranging from 4.5% to 8.2%, reflecting relatively active competition among the next tier. Top AR-HUD suppliers E-LEAD: 159,094 sets installed, 19.7% market share Foryou Multimedia: 133,917 sets installed, 16.6% market share New Vision: 117,172 sets installed, 14.5% market share Huawei Technologies: 96,014 sets installed, 11.9% market share FUTURUS: 93,048 sets installed, 11.5% market share Crystal-Optech: 75,671 sets installed, 9.4% market share Leapmotor: 33,031 sets installed, 4.1% market share PUCHUANG: 27,359 sets installed, 3.4% market share FinDreams Precision: 24,418 sets installed, 3.0% market share Jiangcheng Technology: 21,054 sets installed, 2.6% market share Based on data from January–June 2026, China's passenger vehicle AR-HUD market featured multiple strong players with narrowing gaps, with no clear market leader yet. E-LEAD ranked first with 159,094 sets installed and a 19.7% market share, followed by Foryou Multimedia and New Vision at 16.6% and 14.5%, respectively. The three suppliers each held more than 10% of the market, forming the leading tier. Huawei Technologies and FUTURUS ranked fourth and fifth with shares of 11.9% and 11.5%, respectively, with fewer than 3,000 sets separating them. Crystal-Optech ranked sixth with a 9.4% share, while Leapmotor, PUCHUANG, FinDreams Precision, and Jiangcheng Technology ranked seventh through tenth, each with less than 5%. Overall, the top six suppliers accounted for 83.6% of the market, indicating relatively high concentration, while the small gaps among leading players point to intensifying competition. Top suppliers of integrated center console display Desay SV: 1,240,372 sets installed, 15.1% market share BYD: 957,353 sets installed, 11.7% market share Foryou General Electronics: 699,434 sets installed, 8.5% market share HSAE: 521,694 sets installed, 6.4% market share Innolux: 450,622 sets installed, 5.5% market share HIWAY: 396,337 sets installed, 4.8% market share FULSCIENCE: 305,148 sets installed, 3.7% market share BICV: 288,931 sets installed, 3.5% market share Panasonic: 266,325 sets installed, 3.2% market share Ten Pao: 259,788 sets installed, 3.2% market share Based on data from January–June 2026, China's passenger vehicle center display integration market remained dominated by local suppliers, with strong concentration among leading players and competition across multiple tiers. Desay SV ranked first with 1.24 million sets installed and a 15.1% market share, followed by BYD with 957,353 sets and an 11.7% share. Foryou General Electronics ranked third with a 8.5% share, further highlighting the strength of local suppliers. HSAE, Innolux, and HIWAY ranked fourth through sixth with shares of 6.4%, 5.5%, and 4.8%, respectively, reflecting close competition in the second tier. FULSCIENCE, BICV, Panasonic, and Ten Pao rounded out the top 10, each holding around 3% of the market, underscoring the market's diverse supplier base. Top suppliers of integrated LCD instrument cluster Desay SV: 803,884 sets installed, 10.7% market share Foryou General Electronics: 720,245 sets installed, 9.6% market share DENSO: 699,520 sets installed, 9.3% market share AUMOVIO: 628,899 sets installed, 8.4% market share Tianyouwei: 611,433 sets installed, 8.1% market share Visteon: 413,620 sets installed, 5.5% market share XinTongda: 377,619 sets installed, 5.0% market share BYD: 332,249 sets installed, 4.4% market share HSAE: 309,751 sets installed, 4.1% market share Innolux: 224,695 sets installed, 3.0% market share From January to June 2026, China's passenger vehicle LCD instrument cluster integration market remained highly competitive, with no clear market leader. Desay SV ranked first with 803,884 sets installed and a 10.7% market share, but its lead was limited. Foryou General Electronics, DENSO, and AUMOVIO followed with shares of 9.6%, 9.3%, and 8.4%, respectively, forming a closely contested leading tier. The gap between Desay SV and fourth-placed AUMOVIO was just 2.3 percentage points. Tianyouwei ranked fifth with an 8.1% share, remaining close to the leading group. Visteon, XinTongda, BYD, HSAE, and Innolux ranked sixth through tenth, with shares ranging from 5.5% to 3.0%. Overall, the top 10 suppliers accounted for 68.1% of the market, but no single supplier held more than 11%, making the segment more fragmented than cockpit domain controllers and HUDs. Top smart speech solution suppliers iFLYTEK: 3,191,818 sets installed, 42.4% market share AISpeech: 1,856,416 sets installed, 24.7% market share Cerence: 835,616 sets installed, 11.1% market share DreamSmart: 616,799 sets installed, 8.2% market share Baidu: 326,210 sets installed, 4.3% market share Tesla: 238,800 sets installed, 3.2% market share Xiaomi EV: 186,002 sets installed, 2.5% market share Alibaba: 84,162 sets installed, 1.1% market share XPENG: 70,348 sets installed, 0.9% market share MegaRobo: 47,375 sets installed, 0.6% market share China's passenger vehicle voice supplier market remained dominated by two leading players, with local suppliers holding a strong position and market concentration continuing to rise for the Jan. - Jun. period. iFLYTEK ranked first with 3.19 million sets installed and a 42.4% market share, followed by AISpeech with 1.86 million sets and a 24.7% share. Together, the two suppliers accounted for 67.1% of the market, forming a clear duopoly. Cerence ranked third with an 11.1% share, making it the only foreign supplier among the top three, while DreamSmart ranked fourth with an 8.2% share, supported by its smart cockpit ecosystem. Baidu ranked fifth with a 4.3% share, maintaining a presence in smart cockpit and large-model applications.

 Liked by Annabelle Bouchard, Madeleine Lewis
















 Liked by Annabelle Bouchard, Madeleine Lewis