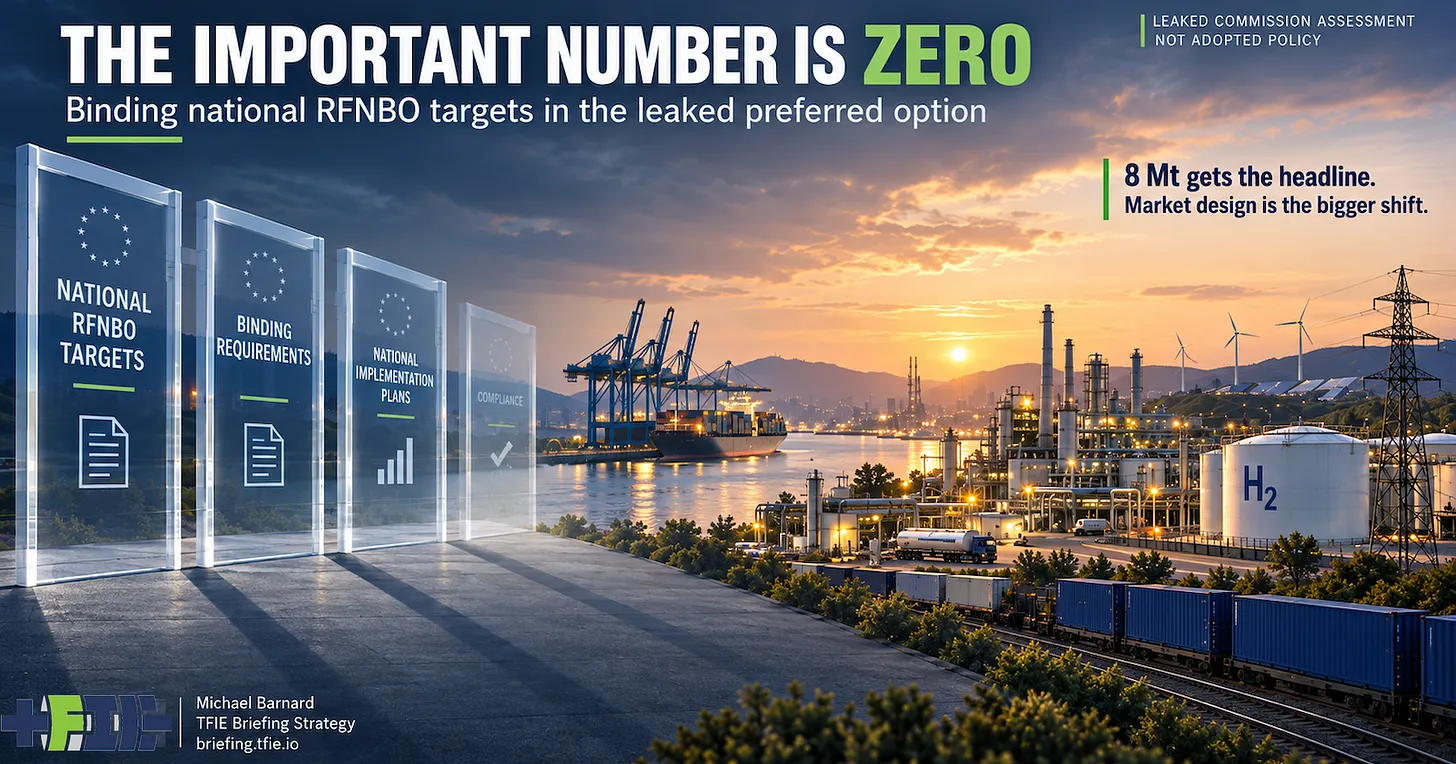
Europe’s current Renewable Energy Directive requires renewable fuels of non-biological origin, or RFNBOs, to account for at least 42% of relevant industrial hydrogen use by 2030 and 60% by 2035, subject to exclusions and flexibilities. Those provisions do more than subsidize hydrogen production. They create a specified market for a specified class of molecule. A leaked European Commission staff impact assessment points toward a different architecture after 2030. Under the L2 measure included in the draft preferred package, binding national RFNBO consumption targets would disappear. In their place would be an indicative EU-level renewable-hydrogen target, financing and enabling measures, and a credit mechanism intended to create demand without requiring every member state to reproduce the same hydrogen market. This remains a draft rather than settled European policy. The document contains placeholders and unresolved methodological material, while the Commission is still preparing the post-2030 renewable-energy framework for a legislative proposal expected before the end of 2026. The useful question is therefore not what Europe has decided, but what the preferred option reveals about the direction Commission staff are examining. The full TFIE Strategy Briefing analysis follows what changes when compliance support can move through credits rather than being tied to national hydrogen-consumption quotas. The deeper issue is whether Europe can keep creating demand for decarbonisation while allowing evidence to change which hydrogen applications, projects and locations receive that demand. The leaked assessment also contains a substantial numerical reset. Its central scenario models 18 million tonnes of electrolytic hydrogen consumption in 2040, compared with eight million tonnes in the low-hydrogen case and 20 million tonnes in the high case. The low-hydrogen pathway would require about 340 TWh of renewable electricity, roughly 335 TWh less than the central scenario, and the assessment notes that lower electrolysis demand could reduce electricity prices and leave more clean electricity available for direct use. That is highly relevant to the electrification debate because hydrogen and direct electricity frequently compete for the same renewable generation. An electrolyser converts electricity into hydrogen with significant energy losses before compression, storage, transport or reconversion are considered. Electric motors, heat pumps, furnaces, batteries and direct electrical industrial processes can often use the original electricity without that conversion chain. The leaked assessment does not settle where hydrogen belongs, but lowering prescribed hydrogen consumption changes the amount of electricity that must be reserved for producing it. There is an important distinction between hydrogen as an existing industrial feedstock and hydrogen as a policy-selected energy carrier. Ammonia, refining and chemical processes already consume hydrogen, most of it produced from fossil fuels, so requirements that lower the carbon intensity of necessary hydrogen can address an existing emissions problem. A technology-specific consumption requirement becomes more consequential when it creates demand for hydrogen in applications where other technologies can provide the underlying service. The current architecture limits part of that competition. Once regulation requires a particular share of qualifying hydrogen to be consumed, market competition can determine which supplier provides that hydrogen, but it has less influence over whether hydrogen itself remains the most economical route to the required service. A credit-based structure could change the allocation mechanism by allowing qualifying renewable-hydrogen production and consumption to satisfy compliance obligations more flexibly across the system. How much flexibility appears in the final legislation will depend on the detailed rules. The draft still contemplates financing, incentives and multipliers rather than a technology-neutral carbon price, and other EU legislation would remain in force unless separately amended. ReFuelEU Aviation retains minimum synthetic-fuel requirements, while FuelEU Maritime provides special treatment for RFNBOs and can trigger a dedicated subtarget. The Alternative Fuels Infrastructure Regulation separately requires deployment of hydrogen refuelling infrastructure on the TEN-T core network. The leaked RED direction therefore should not be read as Europe abandoning hydrogen or suddenly making every decarbonisation technology compete on identical terms. It would leave substantial hydrogen-specific policy elsewhere in the European framework, while the design of credits and multipliers could continue steering demand toward particular applications. What changes is the relationship between the public objective and the prescribed quantity of hydrogen. The existing industrial RFNBO rules create national obligations around consumption of a specified fuel. The leaked alternative would retain public support for renewable hydrogen while giving the compliance architecture more scope to determine where that hydrogen is actually produced and consumed. That distinction matters because industrial transitions generate information after policy is written. Electricity prices differ between locations. Projects experience delays and cost overruns. Customers decline to sign contracts at expected prices. Competing technologies improve. An architecture that can redirect future support as those facts emerge behaves differently from one in which the original volume requirement must continue to be fulfilled somewhere. The draft does not establish that the credit system would produce lower costs or better outcomes, and details such as multipliers could reproduce some of the existing prescription in another form. It does show that Commission staff are examining a framework in which renewable-hydrogen demand can be supported without maintaining the same set of binding national consumption quotas. That is a more fundamental change than choosing eight million tonnes rather than 18 million tonnes in one scenario. The quantity determines how much hydrogen the model contains. The architecture helps determine how Europe decides where hydrogen continues to earn a place. Read the full TFIE Strategy Briefing analysis for the credit mechanics, payer-versus-user implications and the remaining provisions that determine how much competitive discovery the leaked framework would actually permit.

 +44 others