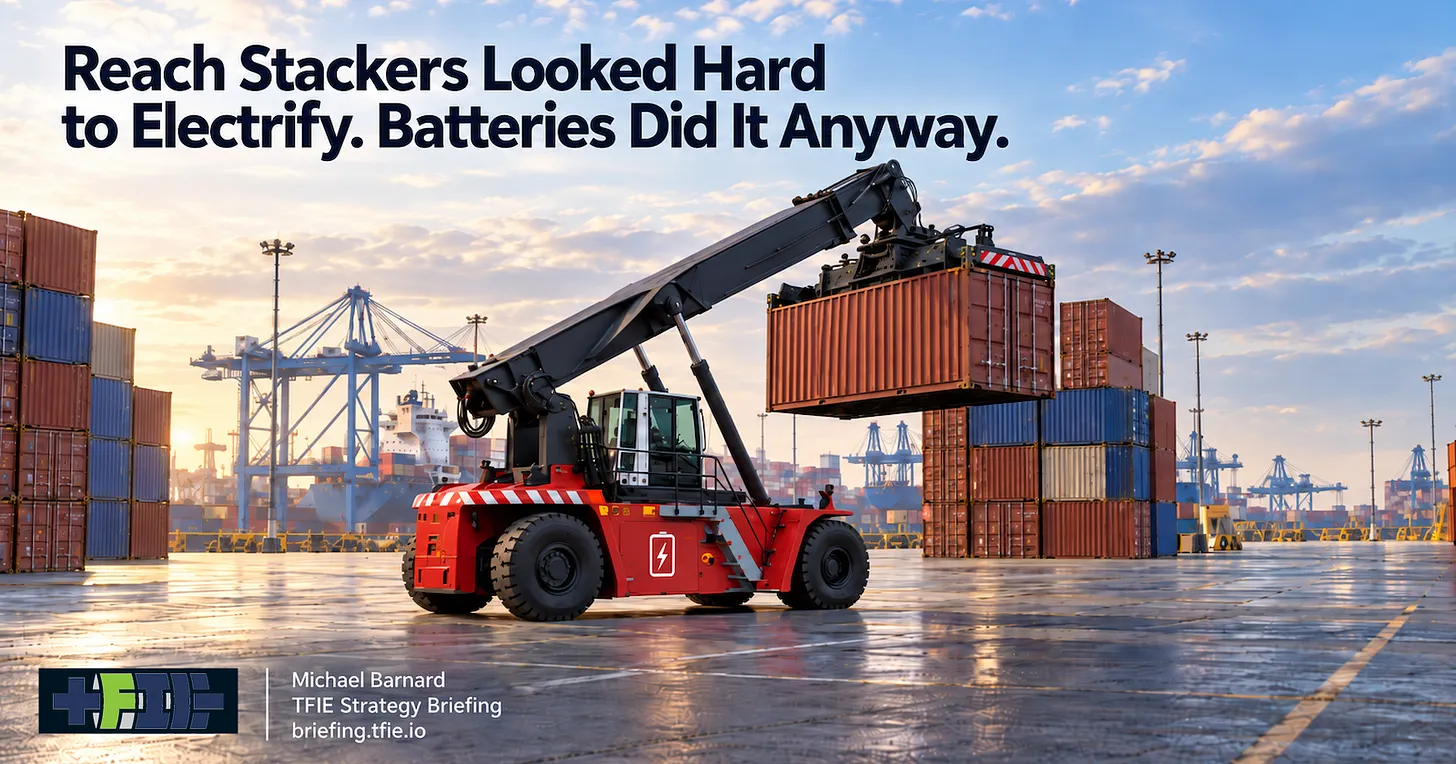
A reach stacker looks like exactly the sort of machine batteries should struggle with. Large models can weigh more than 70 tonnes before picking anything up, then lift loaded shipping containers weighing another 40 tonnes or more several rows deep and several containers high. They work in busy freight terminals where equipment availability matters and where nobody wants an environmental experiment interfering with container movements. Yet the market is developing in the opposite direction from that intuition. My assembled estimate puts the global battery-electric reach-stacker fleet at roughly 1,500 machines, perhaps 15% to 16% of a worldwide fleet around 9,300, while electric machines may already represent close to one-fifth of current production. I started digging into the numbers because Tilbury’s new hydrogen reach-stacker trial made me wonder how the two technologies were actually deploying. The answer says a lot about the difference between a machine looking difficult to electrify and its actual energy requirements. The apparent paradox disappears once the machine is assessed as an operating unit rather than judged by its mass. Reach stackers travel slowly over short distances on paved terminal surfaces. They need very high power for acceleration, lifting and hydraulics, but their average energy consumption is much smaller than their size suggests. They brake frequently, spend time waiting for containers and trucks to be positioned, and repeatedly pass through predictable parts of the terminal. Reliance Transport in New Zealand reports that its 74-tonne SANY electric reach stacker uses about 33 kWh per operating hour while completing full eight-hour shifts and handling around 100 container moves on busy days. The machine can deliver enormous instantaneous power without needing an enormous quantity of stored energy over the course of a shift. That distinction changes the charging problem. Some machines simply carry enough battery for a shift: recent commercial examples use packs around 500 kWh and quote eight, ten or even more hours of operation. Others charge during pauses that already exist in the working day. Kalmar, for example, has designed around high-power charging during ordinary coffee and meal breaks, so an hour of charging can be distributed across periods when the operator would not have been driving anyway. Battery swapping exists as another option for unusually intensive operations, particularly in Chinese equipment, but it is not the trick that made electric reach stackers practical. Most deployments solve the utilization problem more prosaically by matching battery capacity and charger power to the existing work cycle. The economics help explain why operators are doing more than conducting trials. An APM Terminals and DP World analysis in 2023 still estimated battery-electric reach stackers at about 15% higher total cost of ownership than diesel, but expected parity within roughly five years as equipment scale improved and charging was integrated more efficiently into operations. Commercial evidence is now moving through that crossover. Kalmar’s current example calculates a five-year electric TCO 16% below diesel under its stated French operating assumptions, although its model excludes charging and site infrastructure and deserves the normal caution applied to an OEM calculation. More persuasively, Reliance Transport says its overwhelmingly commercially funded electric machine is delivering around 80% lower energy costs and 65% lower maintenance costs than the diesel reach stacker it replaced. The reason is straightforward. A heavily utilized diesel reach stacker can burn tens of thousands of liters of fuel every year. The electric machine pays its battery and equipment premium up front, but every working hour avoids another increment of diesel consumption, while removing the engine, transmission, oil changes and much of the associated maintenance. Hydraulics, tyres, booms and other heavy mechanical systems do not disappear, so electric equipment isn’t maintenance-free. Nor will every terminal produce the same economics: expensive electricity, low equipment utilization or a major grid upgrade can change the calculation materially. But in a busy terminal with reasonable electricity prices, the operating savings can absorb a surprisingly large capital premium. Procurement behaviour is becoming more revealing than another generation of cost models. Westport started with one Kalmar electric reach stacker and followed it with an order for four more. Portonave is adding five electric machines after operating its first. Helsingborg has established a framework for as many as nine, while APM Terminals expects to buy or retrofit roughly 500 electric reach stackers during the coming decade as part of a much larger equipment-electrification programme. Repeat orders matter because the customer buying machines two through five has already seen the first machine’s electricity bills, maintenance requirements, utilization and operator response. These are increasingly asset purchases informed by operating experience rather than bets on a demonstration technology. Hydrogen provides a useful scale check. The Port of Valencia operated an EU-funded Hyster fuel-cell prototype for a few months in 2023, and Tilbury has now started a pre-production trial of an updated version. Those are deployments, but there is no repeat of the battery pattern: a customer operating one hydrogen reach stacker and then returning to order several more. Valencia’s hydrogen pilot ended without a fleet order, and its next documented zero-emission reach-stacker evaluation was battery-electric. The contrast is especially striking because hydrogen’s familiar advantage in heavy machinery is supposed to be utilization: quick refueling should matter where batteries would otherwise require very large packs or excessive charging downtime. Reach stackers increasingly demonstrate that the premise often fails before hydrogen economics even have to be considered. Ports were going to have to reduce diesel emissions from their yards anyway, for climate, air-quality and noise reasons. Reach stackers show what happens when that requirement meets an electric alternative that can also reduce operating expenditure. A machine that visually appears to demand an energy-dense fuel turns out to have a high-power, comparatively low-energy duty cycle inside a compact geography, with natural charging opportunities built into its working day. The surprising number is therefore becoming less the roughly 1,500 battery-electric machines already plausibly operating worldwide and more that a couple of hydrogen trials can still make the two pathways look commercially comparable. For the deployment data, TCO evidence and repeat-order trail behind that conclusion, read the full TFIE Strategy Briefing analysis.