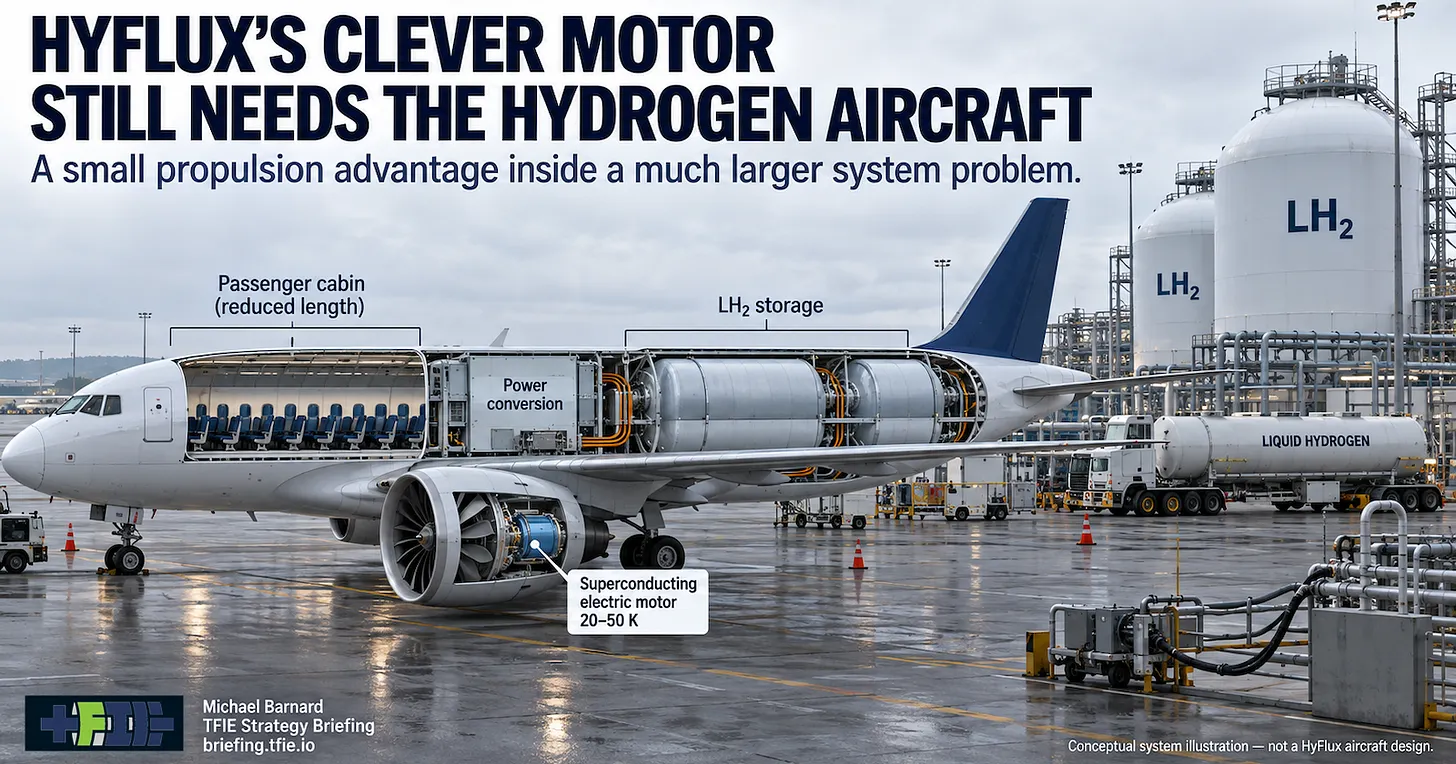
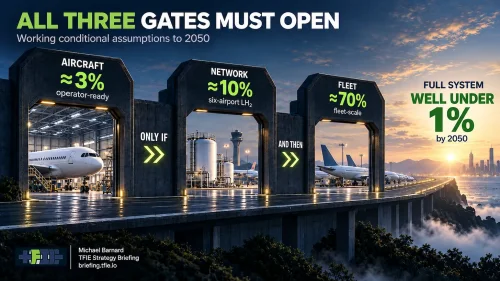
HyFlux has an unusually interesting hydrogen-aviation proposition because the technology at its centre appears somewhat credible, if incredibly difficult to engineer and maintain. The UK company wants to exploit the extreme cold of liquid hydrogen already carried aboard a future hydrogen aircraft to cool a fully superconducting electric motor. Superconductivity can support very high current densities and therefore potentially much more power per kilogram than conventional machines, and HyFlux has been discussing specific power above 20 kW/kg while working toward multi-megawatt aviation propulsion. NASA Glenn’s High-Efficiency Megawatt Motor programme provides a useful reference point, with a partially superconducting machine targeting 16 kW/kg and 99% efficiency. That makes dismissal on first principles the wrong response. The useful questions start with what the impressive motor number actually represents. How much mass has to be added around the electromagnetic machine before it becomes a complete flight-ready propulsion installation? What has actually been demonstrated between earlier 100 kW work and the multi-megawatt architecture HyFlux now discusses? How does the unusual cryogenic operating environment affect an airline propulsion system? Most importantly, does commercial liquid-hydrogen aviation become large enough for this highly specialized motor to have a substantial market? I worked through those questions in considerably more detail in HyFlux Has A Clever Motor. It Still Has A Hydrogen Aircraft Problem., the latest TFIE Strategy Briefing diligence assessment. The deeper analysis examines what the >20 kW/kg claim does and does not establish, the cryogenic propulsion system, development evidence and the commercial aviation pathway HyFlux ultimately depends on. The investment problem is that HyFlux is effectively making two bets. The first is that a fully superconducting aircraft motor can retain an exceptional mass advantage after the hardware needed to turn it into an aviation propulsion system is included. The second is much larger: commercial aircraft carrying liquid hydrogen have to be designed, certified, manufactured and deployed in sufficient numbers for that particular advantage to matter. A conventional electric motor, inverter or controller can potentially serve several growing electrification markets even if one aircraft programme disappears. HyFlux’s aviation proposition only becomes valuable in a world where liquid-hydrogen commercial aviation has already cleared several difficult hurdles. I first assessed hydrogen passenger aviation as a complete system in 2023 and rebuilt that assessment in September 2026 after another three years of airframe design, certification work and airport-infrastructure research. Some of my earlier objections did not survive better evidence, which is exactly what should happen when the evidence improves. Cryogenic tanks have more viable geometries than my arguments about spherical tanks implied, regulators are developing certification pathways, and there is no sound basis for claiming that hydrogen passenger aircraft are inherently incapable of flying or being certified. What remains is less dramatic but more consequential: whether the finished aircraft can preserve a useful passenger, baggage, range and reserve mission, reach repeat production, and find enough airports capable of supplying large quantities of cryogenic hydrogen reliably enough for scheduled operations. The odds are less than 1% that that will happen by 2050 in my opinion. A better motor helps with one important part of that equation because propulsion mass competes directly with passengers, fuel and range. It does not remove hydrogen’s low volumetric energy density, the need for protected cryogenic tanks, the implications for aircraft layout and centre of gravity, or the requirement for a new fuel supply chain at airports. At airline scale, hydrogen supply stops looking like today’s specialist industrial-gas market and starts looking like major energy infrastructure. The airframe and the airport therefore have to develop together, and an improvement in one propulsion component does not break that dependency. The competitive context is also moving while hydrogen aviation develops. Battery-electric aircraft are advancing upward from shorter ranges and smaller payloads, hybrids can extend some of that reach, and conventional turbine aircraft retain the ability to use sustainable liquid fuels without replacing the fundamental aircraft and airport fuel architecture. Those fuels have serious cost and supply constraints, especially synthetic kerosene, but hydrogen does not compete only with synthetic kerosene. It competes with a portfolio that will include batteries, hybrids, biofuels, some synthetic fuels, rail substitution and changes in discretionary travel as aviation energy becomes more expensive. This is why the >20 kW/kg figure is a useful starting point rather than an investment conclusion. Specific power is simply power divided by mass, and aircraft designers care enormously about it, but the commercially relevant boundary is the complete installed system. If HyFlux can demonstrate that its propulsion architecture retains an exceptional advantage once the equipment needed for reliable aircraft operation is included, that would materially strengthen the technical case. Public information does not yet establish that flight-representative result, and moving from a promising motor architecture to a certifiable multi-megawatt propulsion product is not routine scaling. There is a coherent favorable outcome. Airframers could decide to pursue liquid-hydrogen aircraft despite the infrastructure burden, superconducting propulsion could retain enough of its mass advantage to justify the added complexity, and HyFlux and its partners could mature the technology through progressively larger demonstrations. In that world, exploiting a fuel that is already extremely cold as the heat sink for a lightweight motor is elegant engineering and could make HyFlux a valuable supplier. The important distinction is that success of the motor does not cause the rest of that world to exist. Airlines still have to want the aircraft, manufacturers have to build it economically, regulators have to certify it, airports have to build the fuel infrastructure and hydrogen has to compete with alternatives that are improving at the same time. HyFlux may eventually produce an excellent superconducting motor while the liquid-hydrogen passenger-aircraft market remains too small to support the aviation ambitions now being discussed. The full TFIE Strategy Briefing diligence assessment goes into more detailed issues with HyFlux: the superconducting and cryogenic architecture, installed-mass boundary, thermal and fault behaviour, 100 kW development record, execution requirements and the evidence that would materially strengthen or weaken the investment case.